
- Last updated:
- 13 min read
Maya is a freelance UX designer with a single-member LLC. Her clients pay net-30 invoices that clear anywhere from the 3rd to the 24th of the month, and her $1,450 rent is due on the 1st, which is when her business account tends to look thinnest. We built our planning tools after months like hers broke our own budgets, and the fix we trust has two parts. Take owner draws or run payroll, whichever your entity requires, then set a base transfer that never pushes your business account below a reserve on its lowest projected day over the next 90 days.
Quick-Start: How to Pay Yourself a Salary as a Freelancer (The Short Answer and Your Options)
- Find your method from your entity. Default sole prop or single-member LLC means owner draws. S-corp means payroll first. The decision tree below covers the rest.
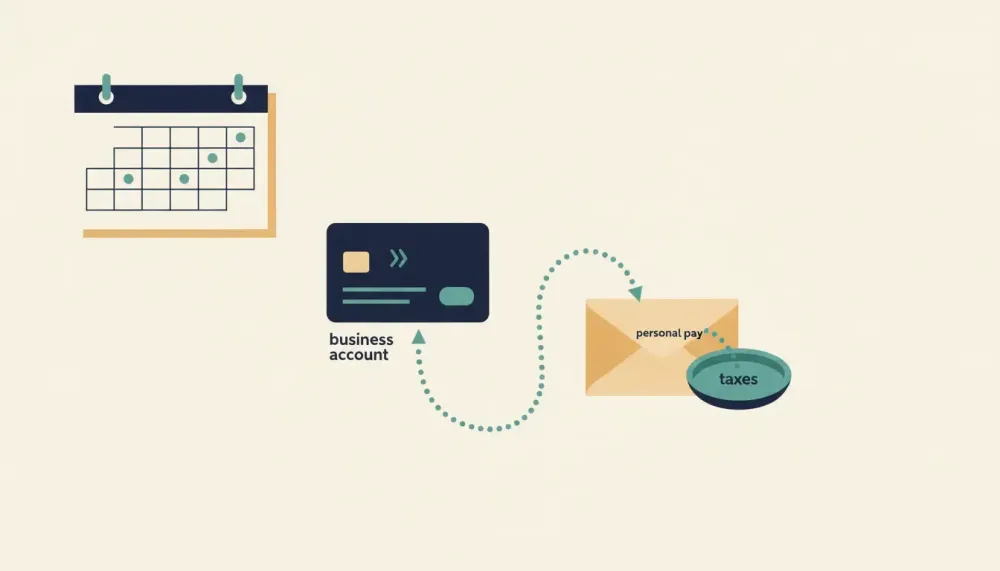
- Separate your money. Use a business checking account, a tax savings account, and your personal checking account.
- Pick a cadence that lands before your big personal bills. Maya pays herself on the 13th and the 28th, so rent on the 1st is never waiting on a client.
- Set aside tax from every payment. Move a fixed share of each client payment to tax savings the day it clears. Maya uses 25%.
- Set a minimum reserve. Use one month of operating expenses plus one pay cycle of base pay. For Maya that's $1,500 + $2,500 = $4,000.
- Calculate base pay, then test it. Start from your trailing collected income. Then check the lowest projected balance over the next 90 days. Your base pay is whichever number is smaller.
- Automate the transfers. Schedule base pay and tax moves so they happen without a decision.
Decision Tree: Owner Draw vs Payroll by Entity
Start with how your business is taxed, not what it's called. An LLC can land in any of these branches.
- Sole proprietor, or single-member LLC with no tax election → owner draw. Business income goes on your own return, and what you take out isn't treated as wages to you, according to the Internal Revenue Service (2025). You pay income tax and self-employment tax on net profit.
- LLC or corporation that elected S-corp status → payroll first, then distributions. You pay yourself a reasonable W-2 salary through payroll before taking distributions, according to the Internal Revenue Service. Profit left after that can come out as distributions, which generally aren't subject to self-employment tax.
- Multi-member LLC or partnership → guaranteed payments and distributions. Partners aren't employees and shouldn't get a Form W-2 for distributions or guaranteed payments, per the Internal Revenue Service (2026). Your share shows up on a K-1.
- C-corp → W-2 payroll for your work. Profit is taxed at the corporate level, and dividends are taxed again on your return. That's why few freelancers choose it.
Maya never filed an election, so she's on the first branch. Most of this article follows her there, with S-corp notes where they differ.
How Entity Type and Taxes Shape How You Pay Yourself
Self-employment tax is figured on profit, not on what you transfer. Sole proprietors and default single-member LLCs report income on Schedule C, and once net earnings from self-employment reach $400, Schedule SE is used to figure self-employment tax (Internal Revenue Service, 2025). That tax runs 15.3% for Social Security and Medicare.
At $10,000 a month in revenue and $1,500 a month in expenses, Maya's business nets about $102,000 a year. She draws $60,000 in base pay. Her self-employment tax is still based on the $102,000 net profit, not the $60,000 she moved. Leaving money in the account doesn't shrink the tax.
Reasonable compensation, briefly
If you elect S-corp status and you work in the business, your salary has to look like what you'd pay someone else to do your job. Look at your duties, your hours, your experience, and market rates for similar roles near you.
Write down how you got the number: the job listings you checked, the hours you work, and the split between client work and admin. Here's an example of the pattern that invites questions. A $20,000 salary sitting next to $100,000 in distributions looks like an attempt to dodge payroll tax. We can't tell you the right salary for your role, and a blog post shouldn't try.
Step-by-Step Setup: How to Pay Yourself a Salary as a Freelancer from Bank Accounts to Payday
Open three accounts
You need business checking for client payments and business bills. You need tax savings for your set-aside. And you need personal checking, where your pay lands.
Here's why the separation matters. Picture paying Maya's $1,450 rent straight from business checking in a tight month. Her books now mix a personal expense with business costs. Untangling that at tax time costs hours, and it muddies what she actually drew.
Set up the pay method
On draws, schedule a recurring transfer from business to personal checking and label it "Owner Draw" in your books. On S-corp payroll, you'll need a payroll service that withholds federal, state, and FICA taxes and files your quarterly and annual returns.
Map payday to your bills
This is the step most guides skip. Put your upcoming bills and income on a calendar view, both personal and business. Then place paydays a few days before your largest personal bills.
Maya's paydays are the 13th and the 28th. The 28th covers rent on the 1st. The 13th covers her $380 car payment on the 15th. Before you lock in dates, check the business side too. On each payday, the projected balance after the transfer should stay above your reserve.
Use buckets, but keep them simple
Use sinking funds for annual renewals and insurance, but keep the core split to three moves: tax first, bills second, base pay third. What's left builds the reserve.
Freelance Salary Calculation: A Repeatable Framework for Irregular Income
Common advice says to average your last few months and pay yourself a percentage. That's a fine starting number. It also ignores timing, and timing is the whole problem for Maya. An average can't tell you that the money arrives on the 24th when your bills hit on the 5th.
So we use two rules.
Reserve rule: your minimum operating reserve is one month of operating expenses plus one pay cycle of base pay.
Base pay rule: your base pay is the smaller of two numbers. The first is your percentage target. The second is the largest amount that keeps your 90-day projected balance above the reserve after upcoming bills, tax set-asides, and transfers.
The IRS estimated-tax rules in Publication 505 (Internal Revenue Service, 2026) tell you how much tax to pay and when. They aren't a formula for how much cash your business should keep. The reserve is your call.
Step 1: Find the percentage target
Maya's last six months of collected payments were $8,000, $12,000, $9,000, $11,000, $10,000, and $10,000. That totals $60,000, or an average of $10,000 a month. If you're not sure what to expect next, our guide to forecasting irregular income walks through it.
Her targets work like this:
- Tax set-aside: 25% of each payment.
- Operating expenses: $1,500 a month for software, insurance, and coworking, paid on the 5th.
- Base pay target: 50% of average revenue, which is $5,000 a month, or $2,500 per payday.
Check that it fits. $10,000 minus $2,500 tax, minus $1,500 expenses, minus $5,000 pay leaves $1,000 a month for the reserve. Her reserve is $1,500 + $2,500 = $4,000.
Step 2: Run the 90-day projection
This example covers October 1 to December 29. Maya starts with $6,800 in business checking, and her tax savings is a separate account. Here's her projected balance on each day something happens:
- Oct 3: Client A pays $4,000, and $1,000 goes to tax. Balance: $9,800
- Oct 5: Expenses of $1,500. Balance: $8,300
- Oct 13: Base pay of $2,500. Balance: $5,800
- Oct 20: Client B pays $5,000, and $1,250 goes to tax. Balance: $9,550
- Oct 28: Base pay of $2,500. Balance: $7,050
- Nov 5: Expenses of $1,500. Balance: $5,550 (lowest)
- Nov 6: Client C pays $6,000, and $1,500 goes to tax. Balance: $10,050
- Nov 13: Base pay of $2,500. Balance: $7,550
- Nov 24: Client A pays $3,000, and $750 goes to tax. Balance: $9,800
- Nov 28: Base pay of $2,500. Balance: $7,300
- Dec 5: Expenses of $1,500. Balance: $5,800
- Dec 8: Client D pays $5,500, and $1,375 goes to tax. Balance: $9,925
- Dec 13: Base pay of $2,500. Balance: $7,425
- Dec 19: Client B pays $4,000, and $1,000 goes to tax. Balance: $10,425
- Dec 28: Base pay of $2,500. Balance: $7,925
The lowest projected balance is $5,550 on November 5. That's $1,550 above her $4,000 reserve. The $2,500 base pay passes, so the percentage target is also the safe number.
Step 3: Re-run it when an invoice slips
On November 20, Client A says the $3,000 due November 24 will arrive December 24 instead. Here's the new path from November 13:
- Nov 13: Base pay of $2,500. Balance: $7,550
- Nov 28: Base pay of $2,500. Balance: $5,050
- Dec 5: Expenses of $1,500. Balance: $3,550 (lowest)
- Dec 8: Client D pays $5,500, and $1,375 goes to tax. Balance: $7,675
- Dec 13: Base pay of $2,500. Balance: $5,175
- Dec 19: Client B pays $4,000, and $1,000 goes to tax. Balance: $8,175
- Dec 24: Client A pays $3,000, and $750 goes to tax. Balance: $10,425
- Dec 28: Base pay of $2,500. Balance: $7,925
The low drops to $3,550, which is $450 under the reserve. The only payday before December 5 is November 28. Maya cuts that one to $2,000, which lifts the December 5 low to $4,050. Her other paydays stay at $2,500.
That $500 cut is annoying. It's also far better than finding out on December 5.
Base Pay vs Profit Sweeps
Base pay is the fixed amount that passes the 90-day low test, transferred on a schedule. It's what your personal bills are built around. It shouldn't change because one month was great.
A profit sweep is an extra draw you take only when the calendar view shows money above the reserve. That has to hold after every upcoming bill, tax set-aside, and base pay transfer for the next 90 days. Sweeps are optional, irregular, and always smaller than the headroom.
Here's Maya's original projection with a sweep. When Client B's $5,000 clears on October 20, her headroom is $1,550. Say she sweeps $1,000, not the full $1,550. That moves her November 5 low from $5,550 to $4,550, still above the $4,000 floor.
Now look at the delayed-invoice version. The same $1,000 sweep would have dropped her December 5 low to $2,550, and the November 28 cut would have needed to be much bigger. That's why we keep sweeps small and re-run the projection before every one.
Two habits keep sweeps clean:
- Label each sweep separately from base pay in your books.
- Move the money to personal checking before you spend it. Don't pay personal bills straight from the business account.
Paying Yourself from LLC: Owner Draw Details and Best Practices
What a freelance owner draw is
An owner draw is a transfer of profit from the business to you. It's a reduction in your equity, not a business expense. Nothing is withheld, which is why the tax set-aside has to happen on its own.
How to record it
Create an equity account called "Owner Draw" or "Member Distribution." Don't put it under expenses. Maya's October entries look like this:
- Oct 13, base pay: Debit Owner Draw $2,500, Credit Business Checking $2,500
- Oct 28, base pay: Debit Owner Draw $2,500, Credit Business Checking $2,500
Reconcile monthly. If draws get recorded as expenses, your profit looks lower than it is, and your tax estimate will be wrong in the direction that hurts.
When to look at switching to payroll
Consider talking to a CPA about an S-corp election when:
- Your profit has been steady for at least a year.
- It's well above a reasonable salary for your role.
- You're ready to run payroll every pay period, including the slow ones.
- Your state's treatment doesn't erase the savings.
You'll often see $70,000 to $100,000 a year in profit cited as the point where the election pays off. We haven't found a source we trust for that cutoff, so treat it as a reason to ask, not a rule.
Taxes and Compliance: Avoid Penalties and Surprises
- Estimated taxes: Payments generally apply when you expect to owe at least $1,000 and your withholding and credits will fall below the smaller of 90% of this year's tax or 100% of last year's tax. That second figure rises to 110% if your income is above the IRS threshold (Internal Revenue Service, 2026).
- Due dates: April 15, June 15, September 15, and January 15 of the following year. Our quarterly tax guide covers how to estimate each one.
- Pay from the tax account, never from checking. In the original projection, Maya's six payments put $6,875 into tax savings by December 19. That's 25% of $27,500. Her January 15 payment comes from there and never touches her projected business balance.
- S-corp payroll: Expect quarterly federal payroll returns, annual unemployment filings, and W-2s. A payroll service handles these, and late filings get penalized fast.
Is 25% enough for Maya? It depends on her bracket, her state, and her deductions. We don't know hers, and you shouldn't trust a blog post that claims to know yours. This is education, not tax advice.
Cash-Flow Smoothing Tactics for Irregular Income
1. The reserve is a floor. Don't schedule anything that would push the lowest projected day below it. If something does, fix it on the paydays before that day, not after.
2. Let the calendar set timing. Paydays go before personal bills. Large business bills go after expected income when vendors allow it. If Maya's annual $1,800 software renewal lands on November 5, her low day, it drops that balance to $3,750, below her $4,000 floor. Moving it to November 8 costs nothing and protects the floor.
3. Follow the pause and reduce protocol. When the lowest projected balance falls below reserve, work down this list:
- Pause profit sweeps.
- Reduce base pay on the paydays before the low day, as in the $2,000 cut above.
- If the low falls below one month of operating expenses, pause base pay and go get money in. Chase the invoice, ask for a partial payment, or invoice early on the next milestone. Deposits, milestone billing, and net-15 terms all shrink the gaps. Our guide to seasonal freelance work goes deeper.
Suppose Client C's $6,000 had slipped from November 6 to December 6 instead. Maya's low would have been $1,300 on December 5. Lifting that to $4,000 would take $2,700 cut from her two November paydays, more than half of the $5,000 she'd normally take. That's why step three is where she'd be.
4. Refill before you raise. After a cut, restore full base pay before taking any sweep.
Tools, Templates, and Providers That Make It Easy
Our free variable income budget template takes your income history and shows your lowest, average, and highest recent months. That's your starting number for Step 1.
Cash Flow Calendar shows upcoming bills and income on a calendar and projects your running balance for every future day. Maya keeps one calendar for business and one for personal. When Client A's payment moved to December 24, she changed one entry and saw the new December 5 low right away.
You can connect a bank account (U.S. and Canada) or enter everything by hand. If you run S-corp payroll, pick a service that files your returns for you.
Common Mistakes to Avoid When Paying Yourself
- Setting pay from today's balance. On October 20, after Client B paid, Maya had $9,550. That balance said nothing about the $3,550 low on December 5 after Client A's payment moved.
- Skipping the tax move "just this once." Every skipped transfer is a January problem waiting to happen.
- Raising base pay after one big month. Take a sweep instead. Raise base pay only after several months where the 90-day low clears the reserve comfortably.
- On S-corp, a salary picked to dodge payroll tax. Document how you set it, and file every payroll return on time.
Your Next Step: Set Your Base Draw Ceiling
- Open your 90-day projection in the calendar view, with your upcoming bills, expected invoices, and tax moves entered.
- Find the lowest projected balance and the date it happens.
- Subtract your reserve from that low. Your upcoming bills are already in the projection, so don't subtract them again. If the result is zero or more, your percentage target passes and becomes your base draw ceiling. If it's negative, cut the paydays before that date by the shortfall.
- Schedule the base pay transfer and an automatic tax move on every client payment. Re-run the projection whenever an invoice slips, and review your targets each quarter.
Written by
Philipp AlbrechtPhilipp Albrecht is the founder of Cash Flow Calendar. He spent years as a freelancer and built the app after missing a rent payment while waiting on client invoices — not because he didn't have the money, but because it hadn't landed yet. Everything on this blog comes from that problem: knowing what's coming in, what's going out, and on which day.
FAQs
Start by listing the next three months of personal due dates on a calendar, then place paydays a few days before the largest ones. If a bill shifts earlier, move the prior payday earlier for that month without changing your long term cadence. Recheck that the business balance still stays above your floor after the change.
Related Articles
Income Smoothing for Freelancers with a Steady Paycheck
Nov 2, 2026
Proof of Income Self Employed With a Dated Payment Log
Oct 31, 2026
Profit First for Freelancers Scheduled on a Calendar
Oct 30, 2026
One Weekly Rule for Freelance Taxes and Set-Asides
Oct 29, 2026
Self Employed Budget on One Calendar, Projected Balance
Oct 26, 2026
Quarterly Estimated Tax Calendar For Freelancers Due Dates
Jun 25, 2026
Free Freelance Cash Flow Forecast Template: 13-Week
Jun 17, 2026
Visual Budget Planner for Gig Workers in 15 Minutes
Jun 17, 2026
Best Gig Economy Platforms to Earn Extra Money by Net Pay
Apr 12, 2026
How to Price Freelance Services: Set Rates and Cash Flow
Apr 12, 2026
Best Tax Advisor for Freelancers and How to Choose
Apr 11, 2026
How to Estimate Quarterly Taxes for Freelancers With 4 Dates
Apr 11, 2026
Tax Deductions for Freelancers You Can Claim This Year
Apr 10, 2026
How to Build a Safety Net as a Freelancer
Aug 19, 2025
Top 7 Budgeting Apps for Freelancers to Manage Finances Efficiently
Aug 18, 2025
The best ways to track expenses as a freelancer
Aug 19, 2025
How to Create an Invoice as a Freelancer
Aug 19, 2025
YNAB (You Need a Budget) for Freelancers: Is It Worth It?
Aug 19, 2025
Wave vs FreshBooks: Which Invoicing Tool is Best for Freelancers?
Aug 19, 2025
The Freelancer’s Guide to Invoicing
Aug 19, 2025
How to Track and Deduct Business Expenses as a Freelancer
Aug 18, 2025
How to Save for Vacation as a Freelancer
Aug 18, 2025
How to Separate Business and Personal Finances as a Freelancer
Aug 18, 2025
How to forecast Income as a Freelancer
Aug 18, 2025

